
South Carolina Issues Guidance on Its New 2026 Income Tax Rules
New guidance explains how South Carolina's revised rates and deductions affect estimated payments and 2026 income tax returns.
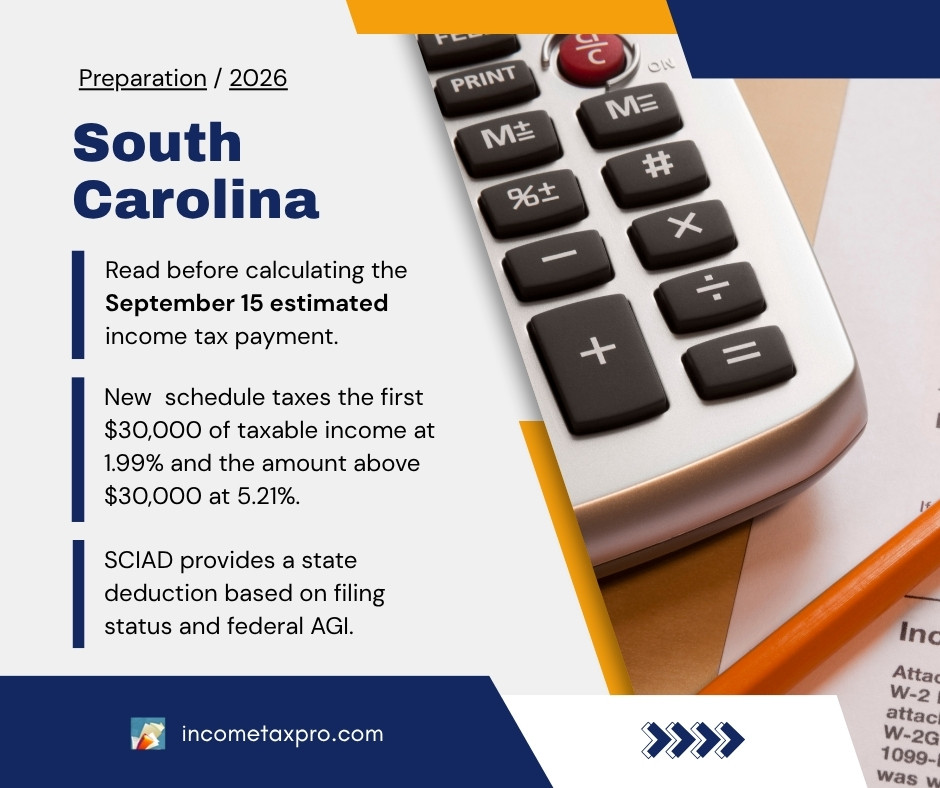
The South Carolina Department of Revenue is asking taxpayers who make estimated income tax payments to review new guidance on the state's 2026 tax overhaul. In a September 1 announcement, the department directed taxpayers to Information Letter 26-20, issued August 31, before calculating their September 15 payment.
The guidance explains Act 110, which Governor Henry McMaster signed on March 30. The law changes both the rates and the income used to calculate state tax, beginning with the 2026 tax year. Taxpayers cannot judge its effect on their bill from the lower top rate alone.
Two Rates and a Different Starting Point
South Carolina's new schedule taxes the first $30,000 of taxable income at 1.99% and the amount above $30,000 at 5.21%. For taxable income of $30,000 or more, the state's calculation is 5.21% of taxable income minus $966. The subtraction accounts for the lower rate on the first portion of income.
The return also starts with federal adjusted gross income, or AGI, instead of federal taxable income. Federal AGI is the amount before the federal standard or itemized deduction and several other deductions used to reach federal taxable income.
Information Letter 26-20 explains that South Carolina no longer adopts those federal deductions. Its list includes the standard deduction, Schedule A itemized deductions, and deductions for qualified business income, seniors, tips, overtime, and car loan interest. A deduction allowed on the federal return therefore may not reduce South Carolina income.
A New Deduction That Decreases as Income Rises
The South Carolina Income Adjusted Deduction, or SCIAD, provides a state deduction based on filing status and federal AGI. The maximum amounts and the income levels at which reductions begin are highlighted in the table below.
| Filing Status | Maximum Deduction | Reduced Above Federal AGI |
|---|---|---|
| Single or Married Filing Separately | $15,000 | $40,000 |
| Head of Household | $22,500 | $60,000 |
| Married Filing Jointly or Qualifying Surviving Spouse | $30,000 | $80,000 |
The deduction phases out completely at federal AGI of $95,000 for Single and Married Filing Separately, $142,500 for Head of Household, and $190,000 for joint filers and Qualifying Surviving Spouse. Those are federal AGI limits, not South Carolina taxable-income brackets.
Taxpayers between the starting and ending income levels receive a partial deduction under the state's formula. Other eligible South Carolina deductions and adjustments still need to be considered. The law also caps the state's nonrefundable Earned Income Tax Credit at $200 per return.
Why Estimated Payments Need Another Look
The department's September announcement urged taxpayers to account for their April and June payments when working out the September installment. Recalculating the annual liability is only part of that review. Withholding and payments already credited to the year also affect the balance.
There is a practical complication for anyone using an earlier worksheet. The linked 2026 SC1040ES, revised October 13, 2025, contains a computation schedule with the previous 0%, 3%, and 6% rates and starts with federal taxable income. Those parts predate Act 110. Use the new law and Information Letter 26-20 for the revised rates, starting point, and SCIAD when reviewing a 2026 estimate.
South Carolina generally requires estimated payments when a taxpayer expects to owe at least $100 with the return, subject to exceptions. The regular fourth installment for calendar-year taxpayers is due January 15, 2027. The SC1040ES instructions also describe prior-year payment rules that may protect taxpayers from an underpayment penalty, so a changed annual estimate does not by itself determine whether a penalty is due.
The New Rules Apply to 2026 Income
The changes apply to 2026 returns, generally due April 15, 2027. They do not change the calculation on a 2025 return filed during 2026. The law allows further rate reductions beginning in 2027 if its revenue conditions are met, but those possible cuts do not change the 2026 schedule.
For the current brackets, deduction details, and a worked tax example, see our South Carolina income tax rates and brackets page. Our South Carolina income tax forms page provides links to available returns and instructions.
References:
- Estimated Income Tax payments due September 15? Read Information Letter #26-20 first.. September 1, 2026. South Carolina Department of Revenue. Retrieved September 20, 2026.
- SC Information Letter #26-20: Individual Income Tax Reform (PDF). August 31, 2026. South Carolina Department of Revenue. Retrieved September 20, 2026.
- Act No. 110 (H. 4216). Approved March 30, 2026. South Carolina General Assembly. Retrieved September 20, 2026.
- Information about H. 4216. April 15, 2026. South Carolina Department of Revenue. Retrieved September 20, 2026.
- 2026 Individual Declaration of Estimated Tax (SC1040ES) and Instructions (PDF). Revised October 13, 2025. Payment procedures and deadlines. The printed tax computation schedule predates Act 110. South Carolina Department of Revenue. Retrieved September 20, 2026.