
Maine Revises Its 2026 Tax Schedule to Include a 2% High-Income Surcharge
The revised schedule adds tax on income above filing-status thresholds while keeping Maine's three regular tax rates.
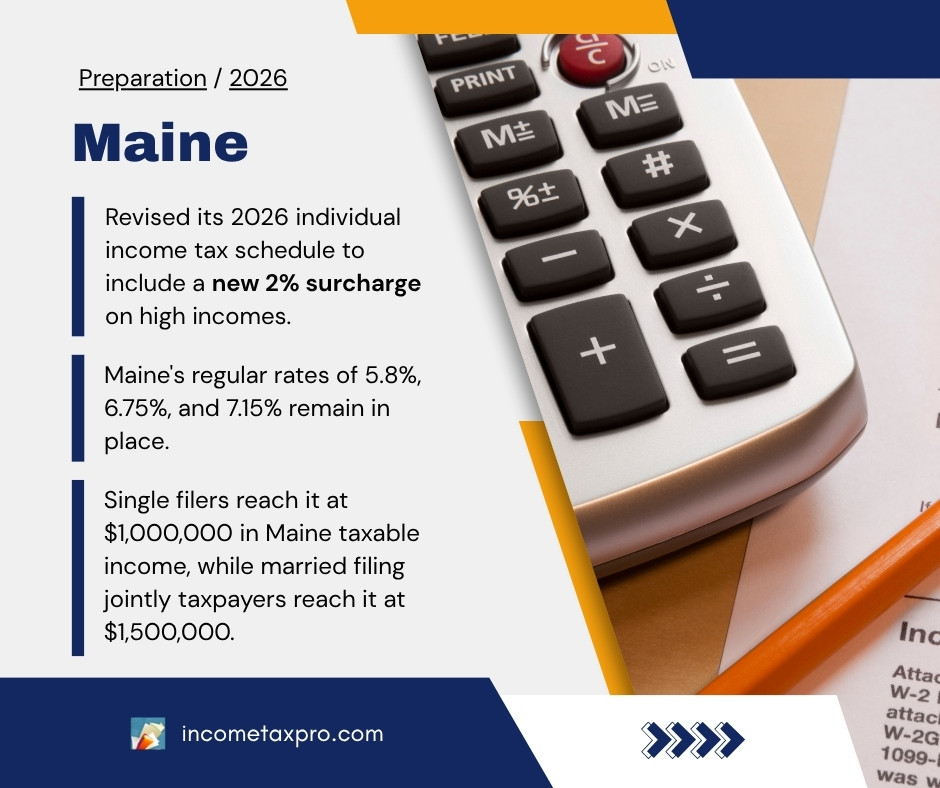
Maine Revenue Services has revised its 2026 individual income tax schedule to include a new 2% surcharge on high incomes. The schedule, marked revised May 20, adds the surcharge to the regular tax calculation for taxpayers whose Maine taxable income exceeds the threshold for their filing status.
The update reflects a provision of the supplemental budget law approved April 10. Maine's regular rates of 5.8%, 6.75%, and 7.15% remain in place. The surcharge is a separate calculation on income above the applicable threshold.
Who Is Subject to the Surcharge?
The threshold depends on filing status. Single filers reach it at $1 million in Maine taxable income, while married taxpayers filing separately have a lower $750,000 threshold.
| Filing Status | Surcharge Applies Above |
|---|---|
| Single | $1,000,000 |
| Married Filing Separately | $750,000 |
| Married Filing Jointly | $1,500,000 |
| Head of Household | $1,500,000 |
| Qualifying Surviving Spouse | $1,500,000 |
These are Maine taxable-income thresholds, not federal adjusted gross income limits. Income at or below the applicable threshold does not generate a surcharge. The law also covers estates and trusts, using the threshold for single individuals.
How Is the Extra Tax Calculated?
Consider a full-year Maine resident filing single with $1.2 million in Maine taxable income. Subtracting the $1 million threshold leaves $200,000 subject to the surcharge. Multiplying that excess by 2% produces $4,000 in additional tax, before considering credits.
The taxpayer still calculates regular income tax using Maine's progressive brackets. Above the surcharge threshold, the 7.15% regular top rate and the additional 2% combine to produce a 9.15% marginal rate. That combined rate applies to the income above the threshold, not the entire $1.2 million.
What Should Taxpayers Review for 2026?
The surcharge applies to tax years beginning on or after January 1, 2026, even though the legislation was approved later in the year. The provision's statutory effective date is July 29, 2026. For calendar-year taxpayers, it affects the 2026 return generally filed in 2027, rather than the 2025 return filed during 2026.
Taxpayers expecting income above the threshold should include the surcharge when projecting their annual state tax and reviewing estimated payments. Looking only at the regular 7.15% top rate would miss the additional liability. The revised schedule specifically cautions that its annual tax calculations are not wage-withholding tables.
The surcharge thresholds will be adjusted for inflation for tax years beginning in 2027. Use the amounts for the year being calculated rather than carrying the 2026 thresholds forward automatically.
For the regular brackets and other calculation details, see our Maine income tax rates and brackets page. Our Maine income tax forms page links to available Form 1040ME returns and instructions.
References:
- 2026 Individual Income Tax Rates (PDF). Revised May 20, 2026. See Note (1) for the surcharge. Maine Revenue Services. Retrieved September 20, 2026.
- 2026 Session Legislation Enacted (PDF). Page 5 explains the surcharge, filing statuses, and statutory effective date. Maine Revenue Services. Retrieved September 20, 2026.
- Public Law 2025, Chapter 650, L.D. 2212 (PDF). Approved April 10, 2026. Part DDDD, pages 220-221, enacts the surcharge and inflation adjustments. Maine Legislature. Retrieved September 20, 2026.